
If you’re applying for disability benefits, you’ve probably run into two similar-sounding programs: Social Security Disability Insurance (SSDI) and Supplemental Security Income (SSI). Both are run by the Social Security Administration. Both pay monthly benefits to people who can’t work because of a disability. And that’s often where the similarities end.
Knowing which program actually applies to your situation, or whether you might qualify for both, can shape everything from how you apply to how much support you receive, and even when your benefits start. Below, we break down what separates SSDI from SSI, updated for 2026, so you know where you stand before you file.
What Is SSDI?
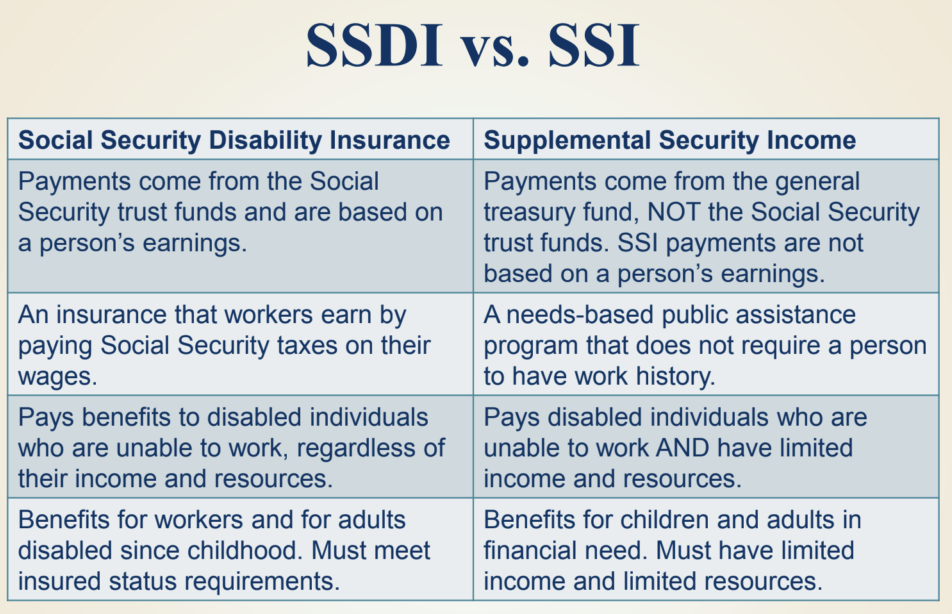
Social Security Disability Insurance is an earned benefit, not a handout. Throughout your working life, a portion of every paycheck went toward Social Security taxes. That money funds the SSDI program, which is why the benefit is tied to your work history rather than your current financial need.
To qualify, you need enough work credits, a measure of how long you worked and paid into the system. In 2026, you earn one credit for every $1,890 in taxable earnings, up to four credits a year, or $7,560 total. How many credits you need, and how recently you earned them, depends on your age when you become disabled; younger workers generally need fewer credits and a shorter recent work history than someone who becomes disabled later in life. If you’re not sure how your work history stacks up, an SSDI lawyer can pull your earnings record and calculate it for you.
Because SSDI is insurance-based, there’s no limit on how much you have in savings, investments, or other household income. What matters is whether you paid in long enough and whether your medical condition keeps you from working. Your monthly SSDI payment amount is based on your average lifetime earnings, similar to how a retirement benefit is calculated, so two people with the same disability can receive very different monthly amounts depending on their earnings history.
What Is SSI?
Supplemental Security Income works on a different principle entirely. Instead of coming from Social Security taxes, SSI is funded through general U.S. Treasury funds, and it’s designed for people with limited income and resources who are 65 or older, blind, or disabled.
There’s no work history requirement for SSI. You could be a child who has never worked, or an adult who hasn’t paid into Social Security in years, and still qualify. Eligibility depends on financial need instead. In 2026, you generally can’t have more than $2,000 in countable resources as an individual, or $3,000 as a couple. Your home and one vehicle usually don’t count toward that limit, though most other savings, investments, and property do.
The maximum federal SSI payment in 2026 is $994 a month for an individual and $1,491 for a couple, though many states add a supplement on top of that amount. For children, a parent’s income and resources are also considered, or “deemed,” as part of the child’s eligibility, which can affect whether a household qualifies. An SSI lawyer can review your specific income and resources to see where you stand.
SSDI vs. SSI at a Glance
| SSDI | SSI | |
| Funded by | Social Security payroll taxes | General U.S. Treasury funds |
| Based on | Your work history and earnings | Financial need, regardless of work history |
| Income/resource limits | None | $2,000 individual / $3,000 couple |
| Who can qualify | Insured workers; some adults disabled before age 22 | Children and adults with limited income and resources |
| Health coverage | Medicare, after a 24-month waiting period | Medicaid, typically right away |
| Back pay before filing | Possible, up to 12 months before your application | Not available; benefits start the month after you apply |
How Applying for SSDI and SSI Is Different
The two programs don’t just differ in who qualifies. They differ in how and when benefits actually reach you. SSDI can pay retroactive benefits for the period before you applied, sometimes up to 12 months prior to your application date, if your medical records show you were already disabled during that time.
SSI doesn’t work that way. Benefits generally begin the month after Social Security approves your application, with no retroactive payments for the time before you filed. That makes the timing of your SSI application especially important, since any delay in filing is time you can’t recover later.
Both programs still go through the same disability determination process once you apply, which is one reason claims for either program can take months to resolve, and why building a complete medical file from the start matters just as much for SSI as it does for SSDI.
How Social Security Decides If You’re Disabled
For adults, Social Security uses the same definition of disability whether you’re applying for SSDI or SSI: a medically determinable physical or mental impairment that prevents substantial gainful activity, and is expected to last at least 12 months or result in death. In 2026, substantial gainful activity generally means earning more than $1,690 a month, or $2,830 a month if you’re statutorily blind.
To reach that decision, Social Security walks through a five-step process: whether you’re currently working above the SGA limit, whether your condition is severe, whether it matches or equals a condition on Social Security’s official list of impairments, whether you can still do any past work, and finally, whether you can adjust to any other type of work given your age, education, and experience. A denial at any one of those steps can end a claim, which is why thorough medical documentation matters just as much for an SSI application as it does for SSDI.
Health Insurance: Medicare vs. Medicaid
The two programs also lead to different health coverage. Approved SSI recipients typically qualify for Medicaid, a joint federal and state program, often as soon as their SSI benefits begin, with little to no additional waiting.
SSDI beneficiaries have to wait. Medicare coverage doesn’t start until you’ve received SSDI payments for 24 months. Once that waiting period ends, you’re enrolled in Medicare Part A automatically, and you can choose to add Part B for an additional monthly premium, which may be deducted directly from your SSDI payment. Depending on your income, some states help cover that premium, and separate low-income assistance may also be available to help with prescription drug costs under Part D.
Can You Qualify for Both SSDI and SSI?
Many people assume they have to choose one program or the other, but that isn’t always true. If your SSDI monthly benefit is low enough, and your income and resources fall within SSI’s limits, you may qualify for both at the same time. Social Security refers to this as a concurrent claim.
Concurrent claims aren’t unusual, especially for people with a limited work history whose SSDI benefit falls below the SSI federal payment amount. In that situation, SSI can supplement a low SSDI check up to the federal benefit rate, which can also open the door to Medicaid coverage while you wait out the 24-month Medicare waiting period under SSDI. The only way to know for certain which programs apply to you is to have your specific work history and finances reviewed.
Which Program Is Right for You?
SSDI and SSI ask two very different questions: how long did you work, and how much financial need do you have. Depending on your history, you may qualify for one, the other, or both, and the answer affects your application, your back pay, and even your health coverage.
An SSD lawyer at Scully Disability Law can review your work credits, income, and resources to help determine which program fits your situation and guide you through the application from start to finish. Contact us today for a free consultation.